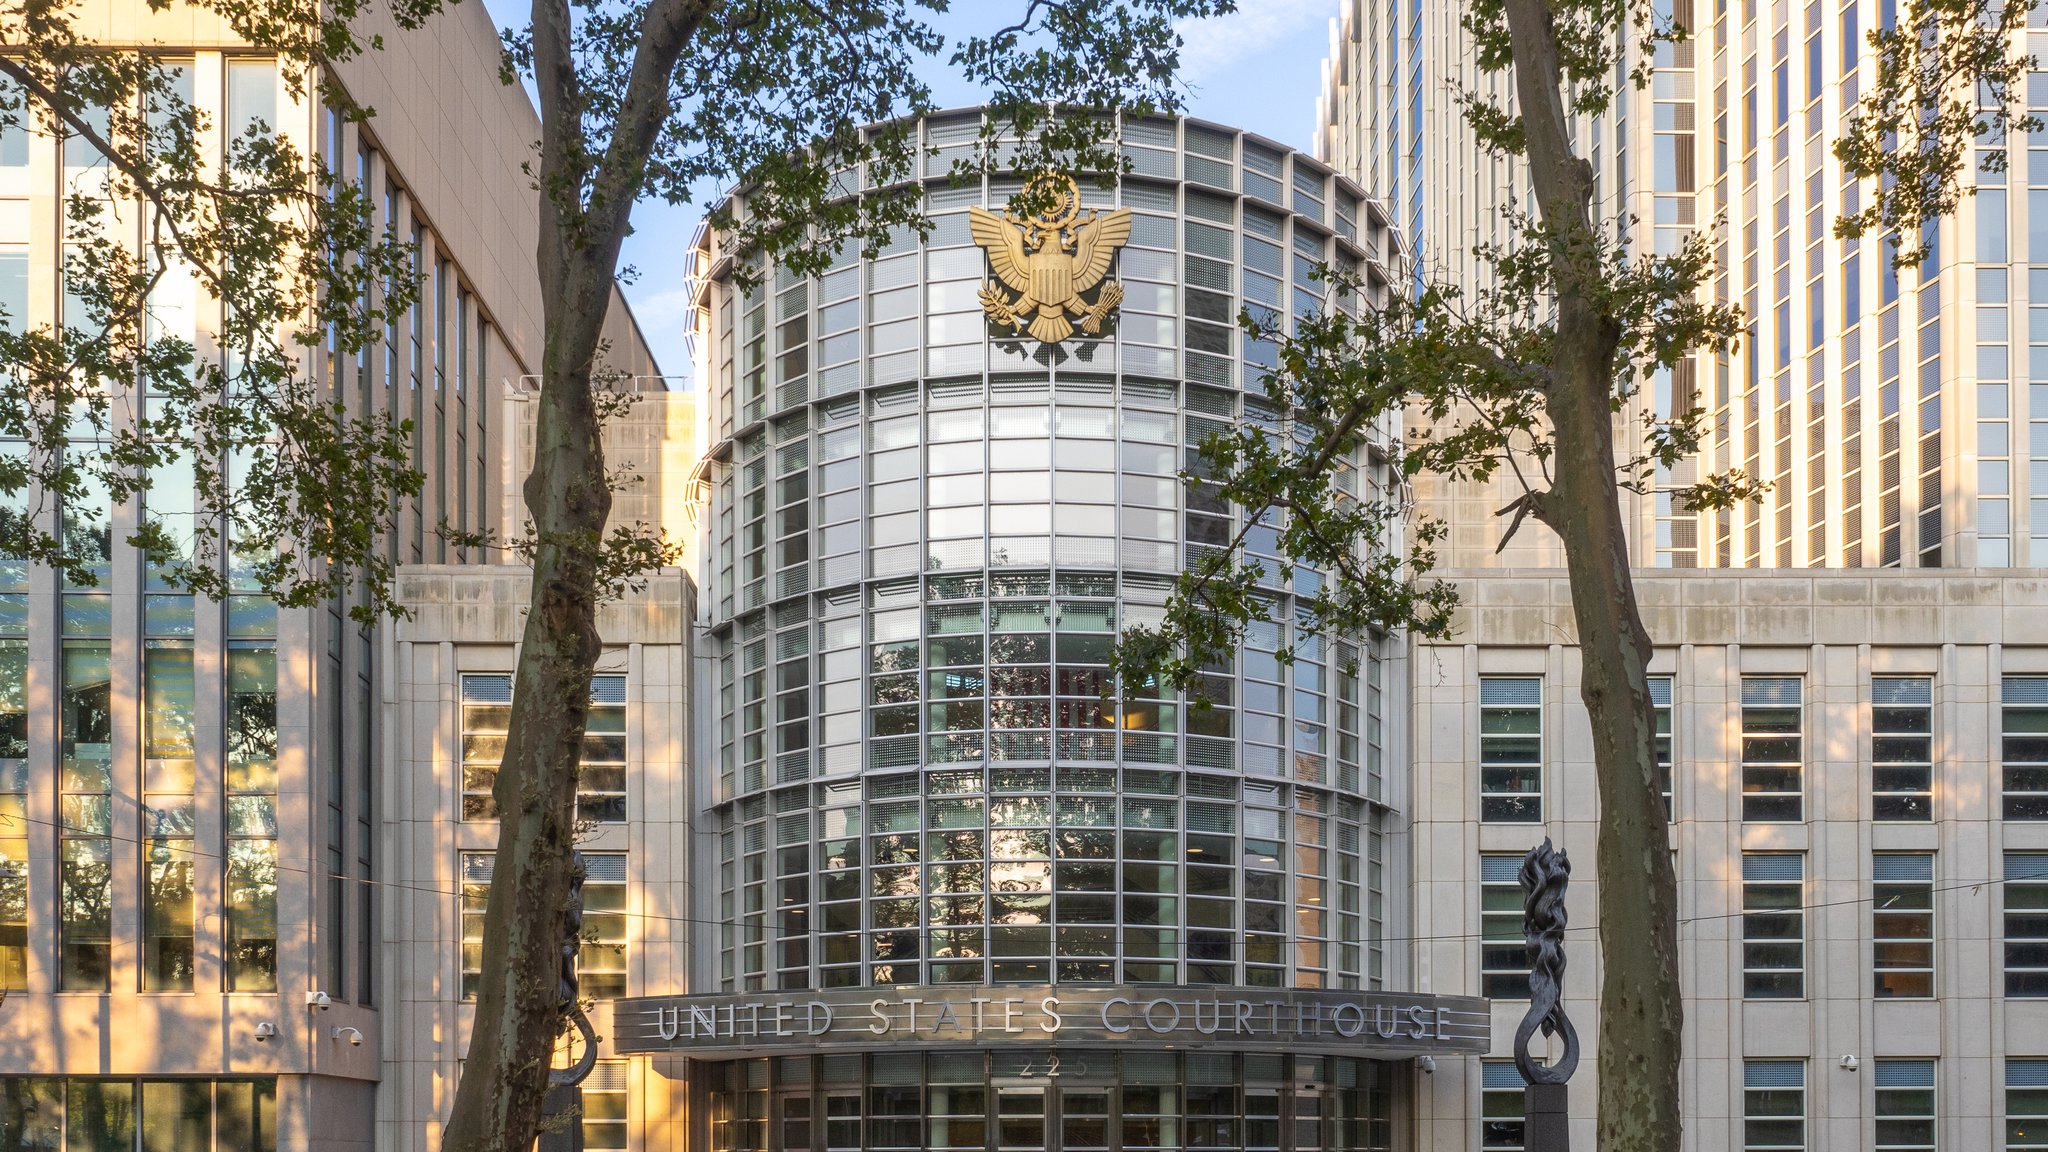
Judge Brian Cogan holds the fairness hearing on the Visa Mastercard settlement at 11:00 AM on November 16 in Brooklyn, and Walmart has asked him to let it leave the class. The deal trims credit interchange and caps standard cards, but its lasting change is to the honor-all-cards rule, which would let a US merchant refuse premium and commercial credit cards for the first time. Whether merchants use that right depends on acquirers more than on the judge.
The Visa Mastercard settlement cuts little and rewrites the rules
The rate relief is small. For five years each network must keep its average effective credit interchange rate at least 10 basis points below the combined average for the 12 months to March 31, 2025, and must not lift any posted credit rate above its March 2025 level, according to the settlement FAQ. Standard consumer credit cards are capped at 1.25% for eight years. The same FAQ puts credit interchange today at 1.15% to 3.15% of the purchase price, and merchants paid an average of 2.35% on Visa and Mastercard transactions in 2024, according to Nilson Report figures cited by Payments Dive.
The rule changes last at least eight years. A merchant could accept or decline commercial, standard and premium credit cards as three separate categories. Issuers must print visual identifiers on newly issued premium and commercial cards. Merchants could surcharge credit cards up to 3% by brand or by product, offer discounts that vary by issuing bank, and test refusing cards at up to 20% of their outlets for 180 days. The rate caps cover credit only. Debit sits under Regulation II, whose 21-cent cap the Eighth Circuit struck down on October 26.
Walmart’s objection is about the release
No merchant can opt out. The settlement binds a mandatory Rule 23(b)(2) class of about 12 million merchants, and the FAQ states that no one can be excluded. In return for the rule changes, every class member gives up claims for injunctive relief over interchange, network rules and “any Merchant Fee” for the longer of five years after the settlement becomes final or eight years after approval.
Walmart filed a 299-page objection on September 14 and, with Circle K and NACS, asked to opt out on constitutional grounds. The court refused its last decertification request, in late 2025. The Merchants Payments Coalition filed for 978 merchants and associations. Its letter says more than 90% of credit card spending runs on rewards cards, so refusing premium cards means refusing nearly every card, and that nothing stops issuers from moving standard cards into a premium tier to escape the 1.25% cap. Visa and Mastercard replied on October 14 that the objectors are “a vocal minority” of the class, Payments Dive reported.
A ruling that lets one retailer leave a mandatory class would invite every large merchant to follow. Visa and Mastercard paid for a release that binds all 12 million, so an exit for Walmart would probably reopen the deal.
Acquirers decide whether premium decline is real
A merchant that wants to refuse premium cards needs its acquirer to identify the card category before authorization, tell the customer at the till and, if it surcharges, price by product. The FAQ sets out the new rights and says nothing about who builds the systems to use them, so small merchants on bundled pricing depend on whatever their processor offers. Australia, which took the opposite path, shows how little a pricing right can achieve. Two decades after it allowed surcharging, only 16% of merchants used it, and Australia has now banned surcharges and left cost control to least-cost routing.
Issuers sit on the other side of the rate. Visa’s client incentives, its payments to financial institutions, merchants and other partners, rose 21% to $5.1 billion in its fiscal fourth quarter, according to its results release. Premium rewards are paid from premium interchange, and a credible threat of decline at large merchants is the only provision in the deal that presses on that rate. New Zealand chose to set the price directly with commercial card caps.
Bottom line
If Cogan approves the deal as written, merchants gain a right to refuse premium cards that few will use until acquirers make category-level decline and pricing cheap, and the release fixes network rules in place for at least eight years. More cards and networks coverage sits on the GL Insight hub.
Watch for:
- Cogan’s ruling on Walmart’s opt-out request
- Acquirer pricing for category-level card decline
- Any issuer move to shift standard cards into premium tiers